Inflationary Pressures in 2026: An Expert Breakdown of How a 3.5% Annual Rate Impacts U.S. Consumer Spending Habits
As we navigate the complexities of the global economy, the specter of inflation continues to loom large. Projections for 2026 suggest an annual inflation rate in the United States could settle around 3.5%. While this figure might seem modest compared to recent peaks, its sustained presence carries significant implications for the average American household and their consumer spending habits. Understanding this potential economic landscape is crucial for both individuals and businesses to prepare and adapt effectively. This comprehensive analysis will delve into the multifaceted ways a 3.5% 2026 inflation impact could reshape the financial fabric of the nation, offering insights from economic experts and actionable strategies for resilience.
Understanding the 3.5% Inflation Projection for 2026
Before dissecting the impact, it’s essential to grasp what a 3.5% annual inflation rate truly signifies. Inflation, in simple terms, is the rate at which the general level of prices for goods and services is rising, and subsequently, the purchasing power of currency is falling. A 3.5% rate means that, on average, goods and services that cost $100 today would cost $103.50 a year from now. Over time, this erosion of purchasing power can significantly alter household budgets and investment strategies.
Several factors contribute to these projections for 2026 inflation impact. Supply chain dynamics, geopolitical events, labor market conditions, and monetary policy decisions all play critical roles. Economists monitor these indicators closely to forecast future price movements. While central banks aim for a stable inflation rate, typically around 2%, persistent pressures can push this higher. The 3.5% forecast for 2026 suggests that underlying economic forces may still be at play, preventing a full return to pre-pandemic price stability. This continued inflationary environment will undoubtedly influence 2026 consumer spending.
The Federal Reserve, through its interest rate adjustments and quantitative easing/tightening policies, attempts to manage inflation. However, these tools have lagged effects and can sometimes be overwhelmed by external shocks. Therefore, consumers and businesses must remain vigilant and not solely rely on policy interventions to mitigate the effects of rising prices. The 2026 inflation impact will largely depend on how effectively these various economic levers are managed and how quickly global supply and demand imbalances resolve.
Direct Impact on Household Budgets: The Shrinking Wallet Phenomenon
The most immediate and noticeable effect of a 3.5% 2026 inflation impact will be on household budgets. For many, this will manifest as the ‘shrinking wallet phenomenon,’ where disposable income buys less than it did before. Essential goods and services, which constitute a significant portion of average household expenditure, are often the first to see price increases. This includes groceries, housing, utilities, and transportation.
Groceries and Food Prices
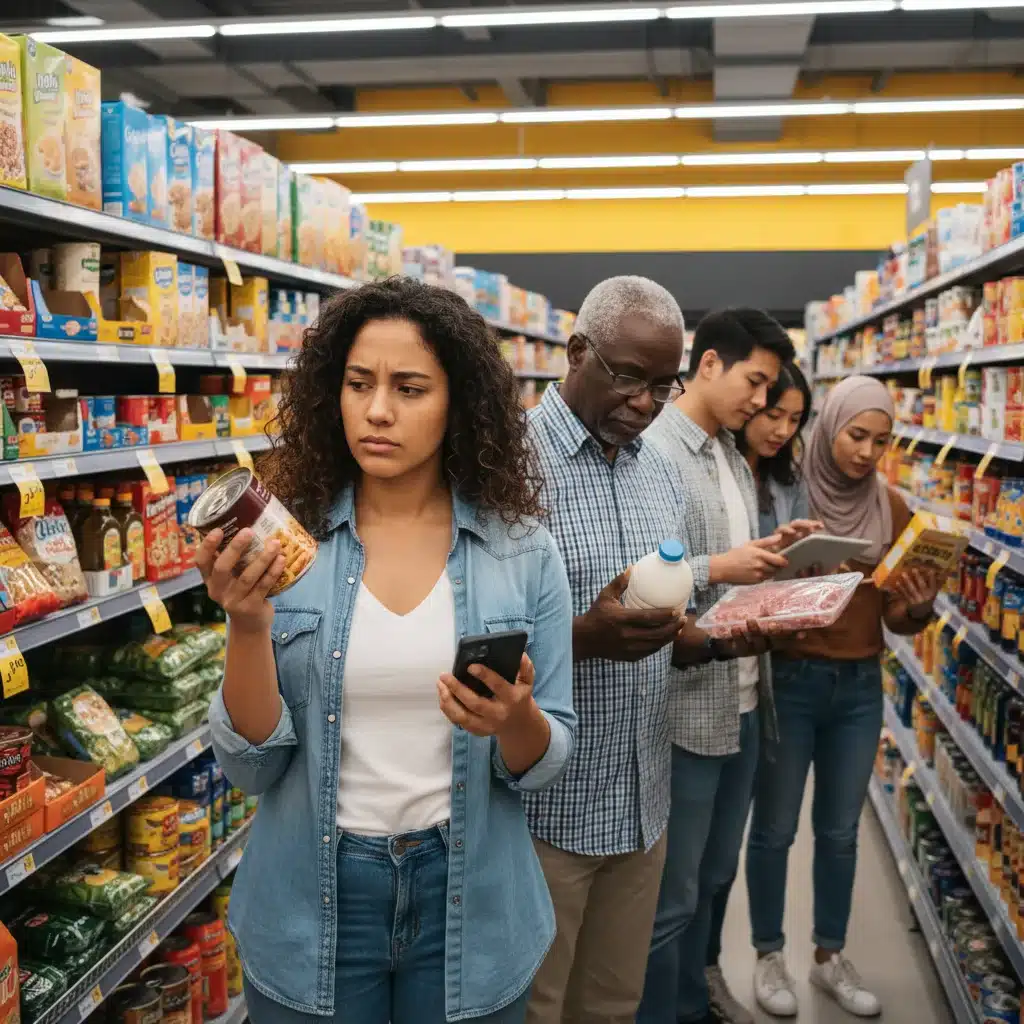
Food is a non-negotiable expense. A 3.5% increase across the board means families will spend more on their weekly grocery runs. This can lead to changes in dietary habits, with some households opting for cheaper, less nutritious alternatives or reducing portion sizes. Budgeting for food will become even more critical, and consumers will likely become more price-sensitive, seeking out sales, discounts, and generic brands. The 2026 inflation impact on food prices could disproportionately affect lower-income households, who spend a larger percentage of their income on food.
Consider a family currently spending $800 a month on groceries. With a 3.5% inflation rate, that same basket of goods would cost approximately $828 a month in 2026, an additional $336 annually. While this might seem small on a monthly basis, it adds up and can strain already tight budgets. This pressure forces consumers to make difficult choices, potentially sacrificing other areas of their spending.
Housing and Utility Costs
Housing costs, including rent and mortgages, are another major component of household spending. While mortgage payments on fixed-rate loans remain constant, property taxes, insurance, and maintenance costs can rise with inflation. For renters, landlords may pass on increased operational costs through higher rents. Utilities – electricity, gas, and water – are also highly susceptible to inflationary pressures, driven by energy prices and infrastructure costs. These increases further squeeze household finances, reducing the amount available for discretionary spending.
The cumulative effect of these rising essential costs means that even if wages see some increases, real wages (wages adjusted for inflation) might stagnate or even decline. This decline in real purchasing power is a core challenge posed by the 2026 inflation impact, forcing a reevaluation of spending priorities for many families.
Shifts in Consumer Spending Habits: From Discretionary to Essential
A sustained 3.5% inflation rate in 2026 will inevitably lead to a significant reallocation of consumer spending. Discretionary spending, which includes non-essential purchases like entertainment, dining out, travel, and luxury goods, will likely bear the brunt of these changes.
Reduced Discretionary Spending
As essential costs consume a larger share of household income, consumers will have less money available for discretionary items. This means fewer vacations, less frequent restaurant visits, delayed purchases of new electronics or clothing, and a general tightening of belts. Businesses that rely heavily on discretionary spending, such as hospitality, retail (non-essential), and leisure industries, could experience reduced demand. This shift is a direct consequence of the 2026 inflation impact, as households prioritize needs over wants.
For example, a family might choose to cook more meals at home instead of dining out, opt for staycations instead of expensive travel, or repair older items rather than buying new ones. These behavioral adjustments are a common response to inflationary environments, as consumers seek to maintain their financial stability in the face of rising prices. The overall volume of 2026 consumer spending might remain stable in nominal terms, but its composition will undoubtedly shift towards necessities.
Increased Focus on Value and Durability
When every dollar counts, consumers become more discerning. There will be an increased focus on value for money and the durability of products. Instead of frequently replacing items, consumers might invest in higher-quality goods that last longer, even if the initial outlay is greater. The ‘fast fashion’ model, for instance, might see a decline as consumers prioritize longevity and practicality. This trend also extends to services, where consumers might seek out more cost-effective solutions or attempt DIY alternatives.
This emphasis on value also means a greater willingness to research and compare prices, read reviews, and seek out promotions. Loyalty to specific brands might diminish if competitors offer similar quality at a lower price point. The 2026 inflation impact will thus foster a more astute and budget-conscious consumer base, driving businesses to adapt their pricing strategies and value propositions.
The Broader Economic Ramifications: Business and Investment
The ripple effects of a 3.5% 2026 inflation impact extend beyond individual households, influencing businesses and the broader investment landscape.
Challenges for Businesses
Businesses face a dual challenge: rising input costs and potentially softened consumer demand. The cost of raw materials, labor, and transportation will increase, eroding profit margins. Companies will have to decide whether to absorb these costs, pass them on to consumers through higher prices, or find efficiencies to maintain profitability. Passing on costs risks alienating price-sensitive consumers, while absorbing them can hurt the bottom line.
Small and medium-sized enterprises (SMEs) are often more vulnerable to inflationary pressures due to their limited bargaining power with suppliers and less diverse revenue streams. They may struggle to compete with larger corporations that can leverage economies of scale. The 2026 inflation impact could therefore lead to business closures or consolidation in certain sectors, particularly those reliant on discretionary spending.
Innovation and efficiency will become paramount. Businesses might invest in automation to reduce labor costs, optimize supply chains to minimize transportation expenses, or explore new product lines that offer greater value to consumers. Those that fail to adapt to the changing consumer landscape shaped by 2026 inflation impact risk falling behind.
Investment Strategies in an Inflationary Environment
For investors, a 3.5% inflation rate in 2026 necessitates a review of portfolios. Traditional safe-haven assets like cash will lose purchasing power over time. Investors will seek assets that can outpace inflation, such as inflation-indexed bonds (Treasury Inflation-Protected Securities – TIPS), real estate, and certain commodities. Equities in companies with strong pricing power – those that can pass on increased costs to consumers without significant loss of demand – may also perform well.
The investment landscape will likely favor sectors that are less sensitive to consumer discretionary spending and those that can demonstrate resilience in a high-cost environment. This could include essential services, healthcare, utilities, and technology companies with strong competitive moats. Diversification and a long-term perspective will be crucial to navigate the challenges posed by the 2026 inflation impact on investment returns.
Strategies for Consumers to Mitigate the 2026 Inflation Impact
While the prospect of sustained inflation can be daunting, consumers are not powerless. Several strategies can help mitigate the 2026 inflation impact on personal finances and maintain purchasing power.
Budgeting and Financial Planning
The cornerstone of managing inflation is a robust budget. Detailed tracking of income and expenses allows individuals to identify areas where they can cut back or reallocate funds. This might involve reducing subscriptions, finding cheaper alternatives for services, or simply being more mindful of daily spending. Regular review and adjustment of the budget are essential as prices continue to shift. Financial planning for 2026 inflation impact should include setting realistic expectations for future costs.
Creating an emergency fund becomes even more critical in an inflationary environment. This fund provides a buffer against unexpected expenses and helps avoid taking on high-interest debt when prices are rising. Aim for at least three to six months’ worth of essential living expenses in an easily accessible, interest-bearing account.
Smart Saving and Investing
Simply letting money sit in a standard savings account where interest rates are lower than inflation means a guaranteed loss of purchasing power. Consumers should explore high-yield savings accounts, certificates of deposit (CDs), or short-term bonds that offer better returns. For longer-term goals, investing in assets that historically perform well during inflationary periods, as mentioned earlier (e.g., TIPS, real estate, certain equities), can help preserve and grow wealth.
It’s also prudent to pay down high-interest debt, such as credit card balances. As inflation rises, interest rates may also increase, making debt more expensive to service. Reducing debt frees up more disposable income, which is invaluable when managing the 2026 inflation impact.
Income Generation and Skill Development
One of the most effective ways to combat inflation is to increase income. This could involve negotiating for higher wages at your current job, seeking promotions, or exploring side hustles. Investing in skills development and continuous learning can enhance employability and earning potential, making individuals more resilient to economic downturns and inflationary pressures. A higher income stream provides a stronger buffer against rising costs, directly mitigating the 2026 inflation impact on your lifestyle.
For those nearing retirement, re-evaluating retirement plans to account for higher future living costs is vital. This might mean working longer, saving more aggressively, or adjusting withdrawal strategies to ensure funds last through an extended period of higher prices.
Government and Central Bank Responses to 2026 Inflation Impact
The role of government and central banks in managing inflationary pressures cannot be overstated. Their actions will significantly shape the economic environment in 2026 and beyond.
Monetary Policy Adjustments
The Federal Reserve’s primary tool for combating inflation is adjusting the federal funds rate. Higher interest rates make borrowing more expensive, which can cool down economic activity and reduce demand, thereby putting downward pressure on prices. However, raising rates too aggressively can risk triggering a recession. The Fed’s challenge will be to find a delicate balance, aiming for a ‘soft landing’ where inflation is brought under control without severe economic contraction.
Their communication and forward guidance will also be crucial in managing market expectations. Clear signals about future policy intentions can help businesses and consumers make informed decisions, potentially easing some of the volatility associated with the 2026 inflation impact.
Fiscal Policy Considerations
Government fiscal policy, including taxation and spending, also plays a role. Excessive government spending without corresponding revenue can fuel inflation by increasing aggregate demand. Conversely, targeted spending or tax relief can help specific sectors or households, though broad measures need careful consideration to avoid exacerbating inflationary pressures.
Policies aimed at improving supply chain resilience, investing in infrastructure, or boosting productivity can have long-term anti-inflationary effects by increasing the economy’s capacity to produce goods and services more efficiently. These structural reforms are essential for sustainable price stability beyond the immediate 2026 inflation impact.
Long-Term Economic Outlook and Adaptation
While a 3.5% inflation rate in 2026 presents immediate challenges, it also necessitates a broader perspective on long-term economic adaptation. Economies are dynamic, and periods of inflation often drive innovation and efficiency gains.
Technological Advancements and Productivity
Technological advancements, particularly in automation and artificial intelligence, could play a significant role in combating long-term inflationary pressures. By increasing productivity and reducing labor costs, these technologies can help businesses produce goods and services more efficiently, potentially offsetting some of the rising input costs. Investment in these areas could be a key strategy for businesses looking to thrive in an environment of sustained 2026 inflation impact.
Global Economic Interdependencies
The U.S. economy does not operate in isolation. Global economic conditions, including the health of major trading partners, geopolitical stability, and commodity prices (especially oil), will continue to influence domestic inflation. A synchronized global effort to address supply chain bottlenecks and foster stable trade relations can help mitigate some of the external inflationary pressures. Understanding these interdependencies is vital for forecasting the full extent of the 2026 inflation impact.
Conclusion: Navigating the 2026 Inflation Landscape
The projected 3.5% annual inflation rate in 2026 is more than just a number; it represents a significant economic force that will reshape U.S. consumer spending habits and demand careful consideration from all sectors of society. From shrinking household budgets and shifts in discretionary spending to challenges for businesses and adjustments in investment strategies, the 2026 inflation impact will be pervasive.
However, armed with knowledge and proactive strategies, individuals and organizations can navigate this landscape effectively. For consumers, this means rigorous budgeting, smart saving and investing, and a focus on increasing income. For businesses, it entails prioritizing efficiency, value, and adaptability. And for policymakers, it requires a delicate balancing act of monetary and fiscal tools to foster stability without stifling growth.
By understanding the mechanisms of inflation and preparing for its potential effects, we can collectively build greater financial resilience and ensure that the U.S. economy continues to move forward, even in the face of persistent inflationary pressures. The conversation around the 2026 inflation impact is not just about weathering a storm, but about strategically positioning ourselves for a future where economic agility is paramount.