Digital Dollar Debate: Economic Implications of a US CBDC by 2026
The prospect of a Central Bank Digital Currency (CBDC) in the United States, often referred to as the ‘digital dollar,’ has sparked intense debate and speculation among economists, policymakers, and the public alike. As discussions continue and research progresses, the possibility of a U.S. CBDC launch by late 2026 is becoming increasingly real. Such a monumental shift in the financial landscape would undoubtedly usher in a new era for the American economy, presenting both unprecedented opportunities and significant challenges. Understanding the profound economic implications of a digital dollar is crucial for all stakeholders, from individual consumers and businesses to financial institutions and the government.
A digital dollar, unlike existing digital payment systems that rely on commercial bank deposits, would be a direct liability of the Federal Reserve. This fundamental difference has far-reaching consequences across various sectors of the economy. From how monetary policy is conducted to the very structure of the financial system, the introduction of a CBDC could reshape everything we understand about money and finance. This article will delve into six critical economic implications that the U.S. economy would likely face if a digital dollar were to be implemented by the proposed timeline.
The journey towards a digital dollar is not merely a technological upgrade; it is a profound economic experiment with the potential to fundamentally alter the fabric of the U.S. financial system. As we navigate this complex terrain, a thorough examination of its potential impacts on monetary policy, financial stability, financial inclusion, privacy, cybersecurity, and global financial leadership becomes paramount. Each of these areas presents a unique set of challenges and opportunities that demand careful consideration and strategic planning. The decisions made today regarding the design and implementation of a digital dollar will reverberate through the economy for decades to come, shaping the future of American prosperity and its standing in the global financial order.
1. Reshaping Monetary Policy Tools and Effectiveness
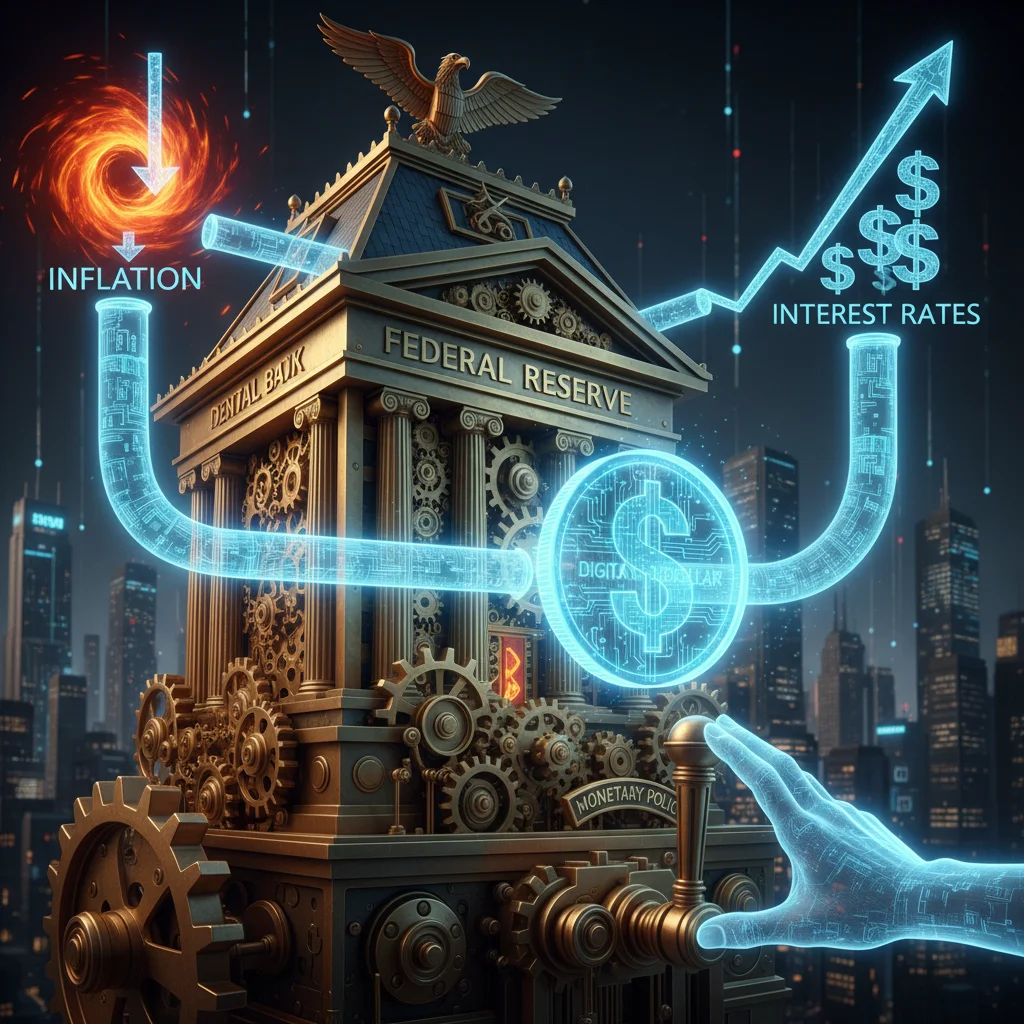
One of the most significant implications of a digital dollar is its potential to revolutionize the conduct and effectiveness of monetary policy. Currently, the Federal Reserve influences the economy primarily through interest rate adjustments and quantitative easing/tightening, which operate indirectly through the commercial banking system. A CBDC could provide the Fed with more direct and potent tools to manage economic activity, particularly in times of crisis or extreme economic conditions. The ability to directly inject or withdraw money from the economy, or to implement nuanced interest rate policies, could significantly enhance the Fed’s response capabilities.
Imagine a scenario where the Federal Reserve could directly pay interest on digital dollar holdings, potentially even negative interest rates during severe economic downturns to stimulate spending. This direct channel bypasses commercial banks, offering a more immediate and potentially more powerful lever for monetary policy. Furthermore, a digital dollar could enable more targeted fiscal stimulus. Instead of broad-based checks, the government could distribute digital dollars directly to citizens, potentially with use-by dates or for specific types of spending, to ensure rapid and effective economic boosts. This precision could dramatically reduce the lag time between policy implementation and economic impact, making monetary policy more agile and responsive.
However, this increased power also comes with considerable risks and complexities. The direct interaction between the central bank and individuals could blur the lines between monetary and fiscal policy, potentially leading to political interference in the Fed’s independence. There are also concerns about the potential for ‘digital runs’ on commercial banks if individuals perceive a CBDC as a safer alternative during periods of financial stress, leading to a massive shift of funds from commercial banks to the central bank. This could destabilize the fractional reserve banking system and necessitate new regulatory frameworks to manage such risks. The design of a digital dollar would need to carefully balance these potential benefits against the risks of increased central bank power and financial system disruption. The digital dollar implications for monetary policy are vast and require meticulous planning.
2. Impact on Financial Stability and the Banking Sector
The introduction of a digital dollar could profoundly alter the landscape of financial stability and the traditional banking sector. As a direct liability of the central bank, a digital dollar would be perceived as the safest form of money, devoid of commercial bank credit risk. This inherent safety could lead to significant shifts in how individuals and institutions hold their money, potentially impacting commercial banks’ deposit bases and their ability to lend. If a substantial portion of deposits migrates to digital dollar accounts, commercial banks could face liquidity challenges, necessitating new funding models or increased reliance on wholesale markets.
During times of financial stress, the ‘flight to safety’ phenomenon could be exacerbated. Instead of moving funds from a struggling bank to another commercial bank, depositors could instantaneously shift their assets into digital dollars held directly with the central bank. While this could prevent bank runs on individual institutions, it could also lead to a systemic drain on the commercial banking system as a whole, potentially triggering a broader financial crisis. To mitigate this risk, policymakers would need to implement robust safeguards, such as limits on individual CBDC holdings or tiered interest rates that disincentivize large-scale conversions from commercial bank deposits to digital dollars.
Furthermore, the banking sector might need to redefine its role. If the central bank takes on a more direct role in payment processing and money holding, commercial banks might focus more on lending, risk assessment, and providing specialized financial services. This could lead to a more diversified and potentially more resilient financial system in the long run, but the transition period would be fraught with challenges. New regulatory frameworks would be essential to manage the transition, ensure fair competition, and maintain overall financial stability in an environment where the digital dollar implications are still unfolding. The ongoing debate around the digital dollar implications for financial stability is a critical component of its evaluation.
3. Enhancing Financial Inclusion and Accessibility
One of the most compelling arguments for a digital dollar is its potential to significantly enhance financial inclusion and accessibility for underserved populations. Millions of Americans remain unbanked or underbanked, relying on costly alternative financial services like check-cashing stores and payday lenders. These individuals often face significant barriers to accessing traditional banking services, including high fees, lack of identification, or insufficient funds to meet minimum balance requirements. A digital dollar, designed with accessibility in mind, could offer a low-cost, secure, and universally accessible payment option.
With a digital dollar account, individuals could receive direct deposits of wages or government benefits, make online purchases, and pay bills without needing a traditional bank account. This could drastically reduce transaction costs for low-income households and provide a safer alternative to carrying cash. Moreover, a CBDC could facilitate easier access to credit by creating a digital financial footprint for those who currently lack one, allowing lenders to assess creditworthiness more effectively. The widespread adoption of a digital dollar could bridge the gap between the financially marginalized and the mainstream economy, fostering greater economic equity.
However, achieving true financial inclusion would require overcoming several hurdles. Ensuring widespread access to digital infrastructure, such as smartphones and internet connectivity, would be paramount. Education and digital literacy programs would also be crucial to empower individuals to use the digital dollar effectively and securely. Furthermore, the design of the digital dollar would need to be user-friendly and cater to the diverse needs of different demographic groups. While the potential for greater inclusion is immense, careful planning and execution are essential to ensure that the benefits reach those who need them most. The digital dollar implications for inclusion are a key driver for its proponents.
4. Privacy Concerns and Data Security
The introduction of a digital dollar raises significant concerns regarding privacy and data security, issues that are at the forefront of public debate. Unlike physical cash transactions, which are anonymous, digital transactions inherently leave a data trail. While a CBDC could offer varying degrees of privacy, from fully anonymous to fully traceable, the extent of privacy afforded will be a critical design choice with profound economic and societal implications. Balancing the need for privacy with the imperatives of combating illicit financial activities like money laundering and terrorist financing will be a delicate act.
If the digital dollar is designed to be fully traceable, it could provide unprecedented tools for law enforcement and regulatory agencies to monitor financial flows. This could significantly enhance efforts to combat financial crime, improve tax compliance, and potentially even track economic activity for statistical purposes. However, such a system also carries the risk of government overreach and surveillance, potentially eroding individual financial privacy and freedom. The specter of a government-controlled financial ledger where every transaction is recorded and potentially scrutinized could lead to public distrust and resistance.
Conversely, a highly private digital dollar, while addressing civil liberties concerns, could complicate efforts to prevent illicit activities. Therefore, the optimal design would likely involve a tiered approach, perhaps allowing for greater anonymity for small, everyday transactions while requiring more identification for larger or suspicious transactions. Robust cybersecurity measures would also be non-negotiable to protect against hacking, data breaches, and fraud. The integrity and trustworthiness of the digital dollar system would depend heavily on its ability to safeguard user data and maintain a high level of security. The digital dollar implications on privacy are arguably one of the most contentious aspects.
5. Cybersecurity Risks and Infrastructure Requirements
The creation and operation of a nationwide digital dollar system would necessitate a robust and resilient cybersecurity infrastructure, presenting both immense challenges and opportunities. A CBDC system would be a prime target for cyberattacks from state-sponsored actors, criminal organizations, and individual hackers due to its central role in the nation’s financial system. A successful breach could not only lead to financial losses but also erode public trust, disrupt economic activity, and potentially compromise national security. Therefore, an unprecedented level of investment in cybersecurity expertise, technology, and protocols would be required to protect the digital dollar infrastructure.
Designing a system that is both secure and scalable would be a monumental task. This would involve employing advanced cryptographic techniques, distributed ledger technologies (if deemed appropriate), and continuous threat monitoring. Regular audits, penetration testing, and incident response plans would be essential to maintain the system’s integrity. Furthermore, the infrastructure would need to be resilient enough to withstand not only cyberattacks but also natural disasters and other disruptions, ensuring continuous availability of payment services. The reliability of the digital dollar would be paramount for its widespread adoption and utility.
Beyond the technical aspects, there are significant operational and governance challenges. Establishing clear lines of responsibility, fostering collaboration between public and private sector entities, and developing international standards for cybersecurity would be crucial. The cost of building and maintaining such an infrastructure would be substantial, but the cost of failure would be far greater. The digital dollar implications for cybersecurity are a critical consideration that must be addressed with the utmost rigor. Ensuring the security of the digital dollar will be a continuous and evolving process, demanding constant vigilance and adaptation to new threats.
6. U.S. Global Financial Leadership and International Implications
The decision by the United States to launch a digital dollar would have profound implications not only domestically but also for its role in the global financial system. As the issuer of the world’s primary reserve currency, the U.S. dollar, the introduction of a CBDC could either reinforce or challenge America’s financial leadership. A well-designed and widely adopted digital dollar could enhance the efficiency and attractiveness of dollar-denominated transactions globally, strengthening its position as the preferred currency for international trade and finance.
A digital dollar could facilitate faster, cheaper, and more transparent cross-border payments, potentially reducing reliance on traditional correspondent banking networks. This could be particularly beneficial for remittances and international trade, making global commerce more efficient. By setting a precedent for a secure and innovative CBDC, the U.S. could influence the design and adoption of other countries’ digital currencies, shaping international standards and norms. This proactive approach could help maintain the dollar’s dominance in a rapidly evolving global financial landscape where other major economies are also exploring or implementing their own CBDCs.
Conversely, a poorly implemented or delayed digital dollar could allow other nations, particularly those with geopolitical ambitions, to gain an advantage in the digital currency space. If countries like China successfully establish their digital currencies as viable alternatives for international transactions, it could gradually erode the dollar’s global standing. The U.S. would need to carefully consider the geopolitical implications of its CBDC strategy, ensuring that it aligns with its broader foreign policy and economic objectives. The digital dollar implications extend far beyond national borders, influencing global power dynamics and the future of international finance.
Conclusion: Navigating the Digital Dollar’s Future
The potential launch of a U.S. digital dollar by late 2026 represents a transformative moment for the American economy. The six economic implications discussed—reshaping monetary policy, impacting financial stability, enhancing financial inclusion, addressing privacy concerns, mitigating cybersecurity risks, and influencing global financial leadership—are interconnected and complex. Each presents a unique set of challenges and opportunities that demand careful consideration, extensive research, and robust public debate.
While a digital dollar holds the promise of a more efficient, inclusive, and resilient financial system, its successful implementation hinges on meticulous design, comprehensive regulatory frameworks, and a clear understanding of its potential ripple effects. Policymakers must strike a delicate balance between innovation and stability, ensuring that the benefits of a CBDC are realized while mitigating its inherent risks. The decisions made in the coming years will not only determine the future of money in America but also profoundly impact its economic prosperity and global standing for generations to come. The digital dollar implications are a testament to the magnitude of this financial evolution.
The journey towards a digital dollar is not merely a technological upgrade; it is a fundamental re-evaluation of the role of money, central banks, and the financial system itself. As the debate continues, it is imperative for all stakeholders to engage constructively, providing insights and perspectives that will help shape a digital dollar that serves the best interests of the American people and strengthens the nation’s economic future. The digital dollar implications are too significant to ignore, requiring a thoughtful and strategic approach to its potential implementation.